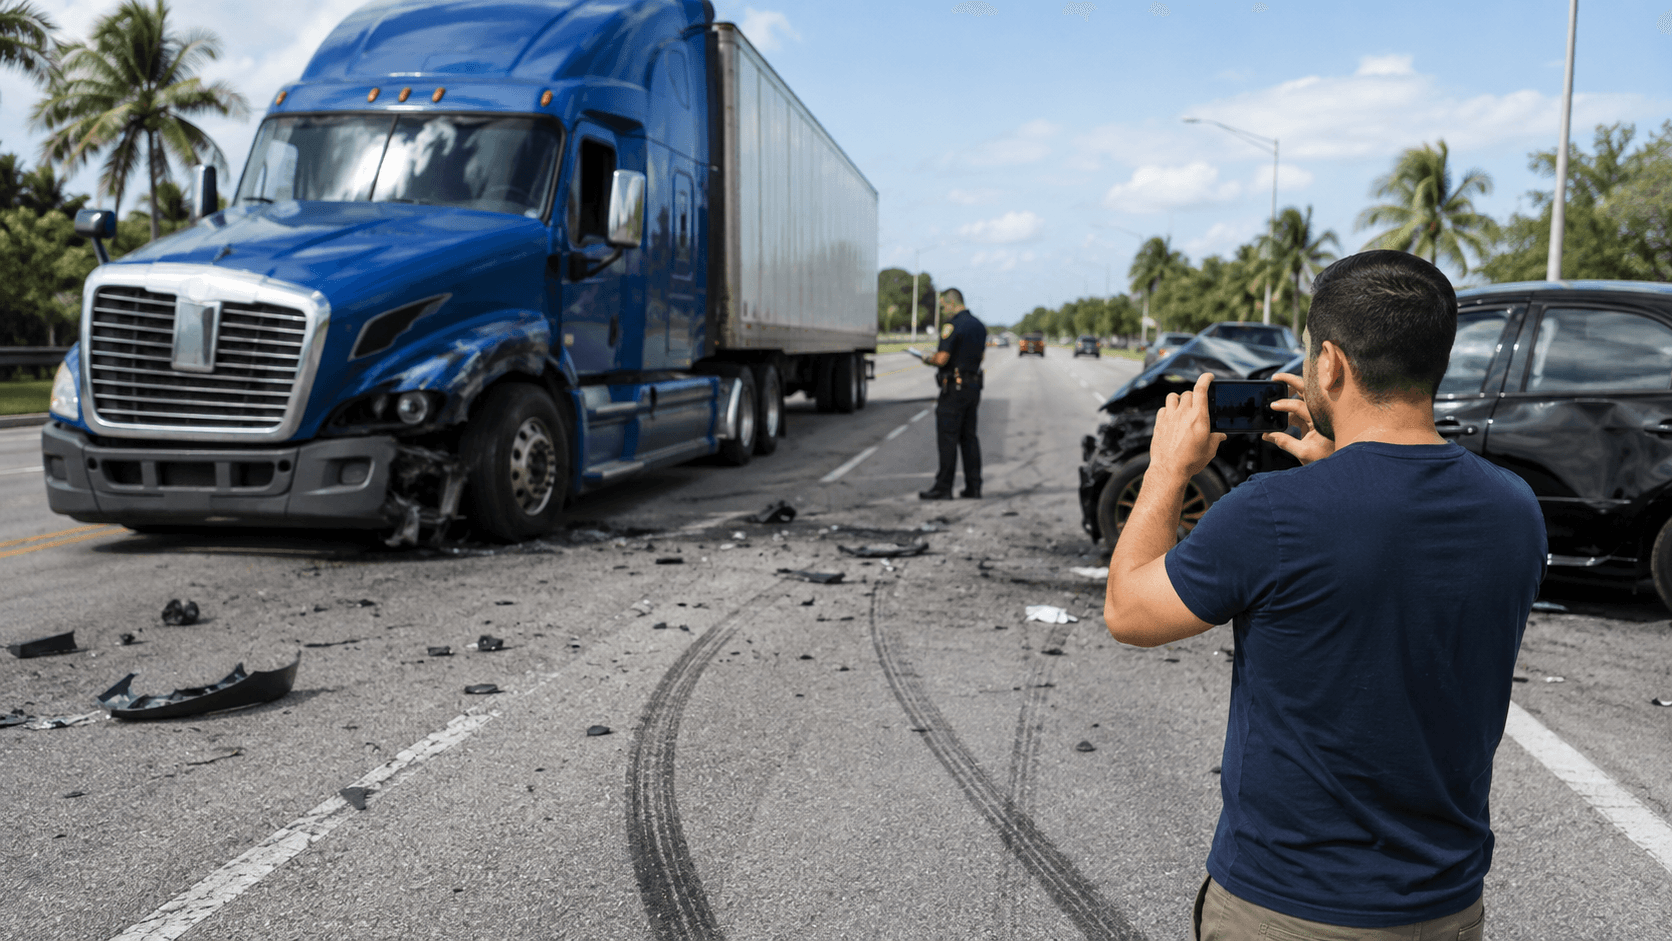
A serious crash can create expenses long before the insurance questions are sorted out. Medical visits, missed work, pain, and uncertainty can pile up quickly, and the driver who caused the accident may not have enough insurance to respond.
That is where uninsured and underinsured motorist coverage deserves close attention. In Florida, UM coverage may provide another source of recovery through your own policy or a qualifying household policy when the at-fault driver cannot cover the loss.
The best time to understand this coverage is before a crash. The next best time is before you resolve a claim or sign a release.
What is UM coverage in Florida?
UM coverage stands for uninsured motorist coverage, and it is often paired with underinsured motorist coverage as well. In practical terms, it may help protect you when the at-fault driver cannot fully pay for the harm they caused.
This can happen in several ways. Sometimes the other driver has no bodily injury insurance at all. Sometimes they have some coverage, but not enough to match the seriousness of the injuries. In other cases, the driver is never identified because the crash was a hit and run.
When that happens, UM coverage may step in through your own policy and help cover losses that otherwise might go unpaid.
Why UM coverage matters so much in Florida
Florida drivers are required to carry certain coverage, but that does not mean every at-fault driver has enough bodily injury coverage to pay for serious injuries. A crash can leave an injured person dealing with treatment, wage loss, and long-term pain while the other driver has limited insurance.
UM coverage can change that conversation. Instead of relying only on the at-fault driver, the injured person may be able to look to their own policy for additional protection, depending on the coverage purchased and the facts of the crash.
What UM coverage may help pay for
UM coverage may apply to losses such as medical expenses, future care, lost wages, reduced earning ability, pain and suffering, and other damages tied to the crash. The available recovery depends on policy limits, injuries, liability, and how the claim is documented.
It is still important to preserve medical records, work restrictions, wage proof, crash evidence, and insurance communications. UM is insurance coverage, not automatic payment without proof.
Free Consultation
Have questions about your next step?
A short conversation can help you understand what records matter, how insurance may respond, and whether legal help makes sense for your situation.
How UM differs from PIP and bodily injury coverage
PIP is usually the first layer for many Florida crash-related medical bills and some lost wages, regardless of fault. Bodily injury coverage belongs to the at-fault driver and may respond when that driver caused harm.
UM coverage is different because it is purchased by the injured person or a qualifying household member. It may become important when the at-fault driver has no bodily injury coverage, too little coverage, or cannot be identified after a hit-and-run.
Do not assume you do not have UM coverage
Coverage can depend on more than the card in the glove compartment. Declarations pages, rejection forms, stacked or non-stacked coverage, household policies, residency, and vehicle status may all matter.
If the other driver appears uninsured or underinsured, review the actual policies before treating the case as limited. A quick assumption can leave useful coverage undiscovered.
What to do after a crash involving an uninsured driver
Report the crash, get medical care, preserve photos and witness information, and notify your insurer as required by the policy. Keep claim numbers, adjuster names, medical bills, repair estimates, and all written communication in one place.
Be careful with recorded statements and broad releases. If the insurance picture is unclear, it may be wise to get legal guidance before resolving the claim.
Talk to Pipas Law Group about UM coverage
If you were hurt by an uninsured or underinsured driver in St. Petersburg, Tampa, Pasco County, New Port Richey, or elsewhere in Florida, Pipas Law Group can review the available coverage and the records needed to support the claim.
A coverage review can help clarify whether PIP, bodily injury coverage, UM coverage, health insurance, or another source may apply before you make settlement decisions.
Frequently Asked Questions
Why UM Coverage in Florida Could Save You Thousands of Dollars FAQs
Is UM coverage required in Florida?
UM coverage is not automatically required in every Florida auto policy, but insurers must address it through the policy process. Whether it exists in a specific case depends on the policy documents and any valid rejection or selection forms.
Can UM coverage apply after a hit-and-run?
It may, depending on the policy and facts. Police reports, witness information, vehicle debris, video, and prompt notice to the insurer can all matter in a hit-and-run UM claim.
Can I use UM coverage if the other driver has some insurance?
Possibly. Underinsured motorist coverage may matter when the at-fault driver has bodily injury limits, but those limits are not enough for the injuries and losses involved.
Should I accept the at-fault driver's policy limits right away?
Not without reviewing medical needs, liens, UM coverage, and any release language. A fast limits offer may still require careful planning before it is accepted.
Talk to Pipas Law Group
Have questions after an accident?
The Pipas Law Group team can review the details, explain what may matter, and help you think through your next step.